Home · Costs & Insurance
Stamford fire damage costs in 2027: the furnace event filled the colonial with soot on the coldest week of the year sets the number
How much does fire damage restoration cost in Stamford in 2027, and does insurance cover it?
Fire is the most commonly covered large loss in a homeowners policy, and costs follow the scope shape: a contained kitchen fire with whole-house smoke is a cleaning and odor job in the thousands, while structural fire with rebuild runs far higher and is priced from the written scope after the scene is released. In Stamford the deciding local variable is this: winter heating systems in the older colonial stock run hard for months and chimney and furnace events follow, northern wooded lots put leaf and brush exposure against siding, and downtown cooking fires in dense apartment stock move smoke through shared shafts. This 2027 guide is compiled from the latest published national figures and local data for the covered ZIP codes 06901, 06902, 06903, 06905, 06906, 06907.
In Stamford, a fire damage price starts with the local read. Homes here are older colonial and cape homes in the residential sections, postwar ranch and split level homes in the northern neighborhoods, high rise and apartment stock downtown and along the harbor, and newer townhome stock near the corridors, and the pattern behind most calls is plain: winter heating systems in the older colonial stock run hard for months and chimney and furnace events follow, northern wooded lots put leaf and brush exposure against siding, and downtown cooking fires in dense apartment stock move smoke through shared shafts. The bands below are the latest published national guide ranges for this trade, framed for Stamford homes, where the documented read, not the first guess, decides the scope.
Compiled from published national guides and local data; reviewed by the Rippowam River Fire Restoration research team. Last reviewed November 16, 2026.
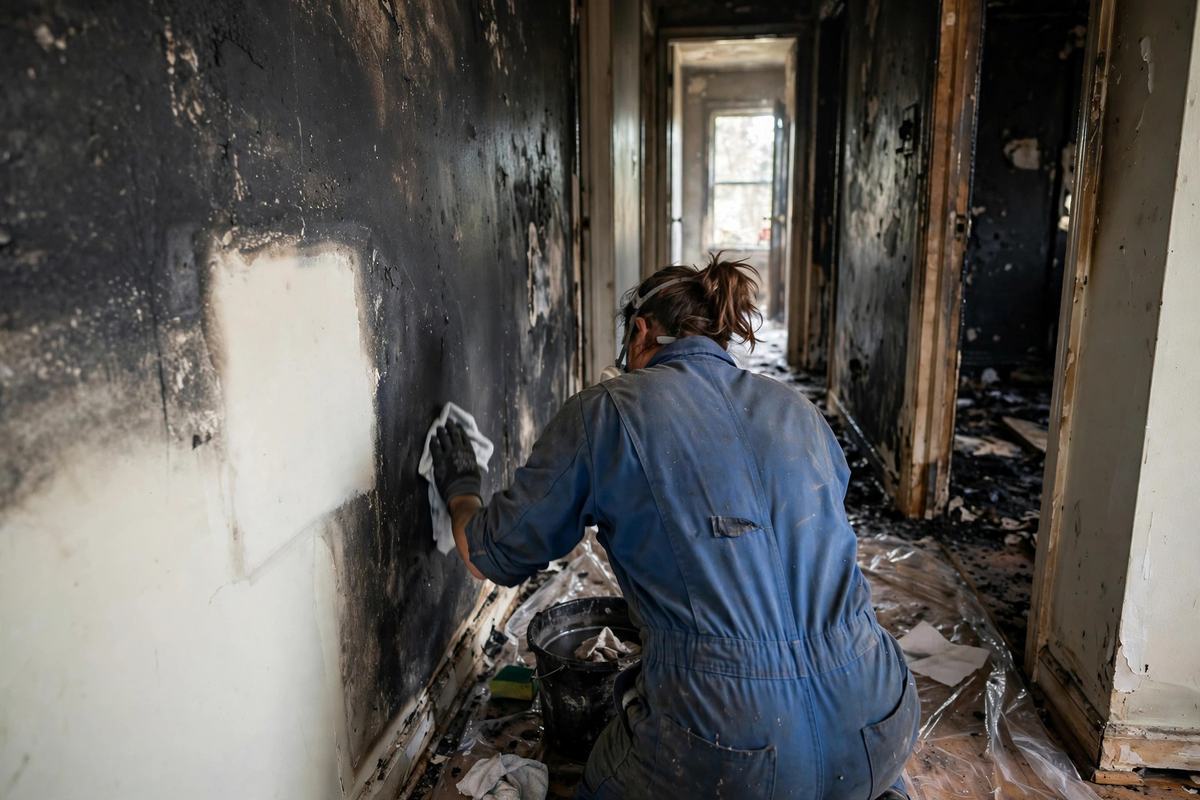
Typical cost ranges
| Job | Typical range | What moves it |
|---|---|---|
| Board up and site securing | Hundreds in most cases | Homes here are colonial and cape sections, northern ranch and split level stock, and downtown high rise homes, and that stock sets access, materials, and time on this line of the scope. |
| Soot and smoke cleaning, whole home | Thousands depending on travel | The Rippowam River side of the service area sets the conditions for this work in Stamford; the firm figure is the written scope, not a phone range. |
| Contents cleaning and pack out | Priced by inventory | Priced from the documented read in Stamford: winter heating loads in older stock, wooded lot exposure in the north, and shared shaft smoke travel downtown drive the call pattern, and the written scope names what the number covers before work starts. |
| Structural repair after cleaning | Thousands depending on loss | In Stamford the local driver is plain: winter heating loads in older stock, wooded lot exposure in the north, and shared shaft smoke travel downtown drive the call pattern. The note on the scope should say how that driver changed the price. |
Guide ranges only. The firm figure for a Stamford home is the written scope built from the documented read, never a phone quote.
How insurance pays for this work
The deductible question
Most homeowners deductibles in this area run $500 to $2,500, with the fire itself almost always a covered sudden event. The fight is rarely about coverage and usually about scope: photograph every room before cleaning, keep the contents inventory, and let the documentation walk happen while the soot record is still undisturbed.
Request a callback
Prefer to talk later? Leave your details and an independent local pro will call you back. No charge to you, no obligation.
Rippowam River Fire Restoration is a free referral service. Submitting this form connects you with independent local contractors who provide the work.